Short-Sighted Climate Goals: It Is Impossible to Expand Electrical Grids to Support EV Conversion

Short-Sighted Climate Goals: It Is Impossible to Expand Electrical Grids to Support EV Conversion

Short-Sighted Climate Goals: It Is Impossible to Expand Electrical Grids to Support EV Conversion
June 4, 2026

A woman in sunglasses stands next to a gray electric car charging at a green charging station in a modern urban setting.
A full conversion of the world’s vehicles to electric vehicles would increase electricity demand to a level that would make the necessary grid expansion and power generation capacity impossible to achieve. Photo courtesy of Chargie.

The net-zero crowd wants the United States and Europe to transition to all-electric vehicles by 2035. Achieving that goal would require an enormous expansion of the electrical grid, on a scale that is both financially and physically impractical, if not impossible.

Several reports estimate that a full conversion to electric vehicles would increase overall electricity demand by about 10%, a level they already conclude would be difficult to support. However, those projections overlook a number of factors. In reality, a complete conversion would likely increase electricity demand by multiples of those estimates, transforming an already impractical undertaking into an impossible one.

At the end of 2024, the global electric car fleet had reached almost 58 million, about 4% of the total passenger car fleet. That fleet consumed around 180 TWh of electricity in 2024, representing approximately 0.7% of total global final electricity consumption. Scaling from those figures, if every vehicle on earth were converted to electric, the straight-line projection yields roughly 3,000 to 3,400 TWh of additional annual electricity demand, which is against the IEA’s reported global consumption of 30,856 TWh in 2024 represents approximately a 10% increase.

That straight-line projection is almost certainly a severe undercount, for five structural reasons.

First, long-haul trucking is nearly absent from current EV data. Heavy-duty long-haul trucks generate more than half of road freight oil demand today, yet remain one of the hardest vehicle segments to electrify. In terms of power demand, full truck electrification could add approximately 3% to global electricity consumption by 2050, on top of passenger vehicle demand, with fuel consumption for heavy trucks running 2 to 3 times higher per vehicle than for light trucks, and yearly distances 3 to 5 times greater in long-haul applications. Current EV electricity consumption figures are built almost entirely on passenger car data and carry none of that freight burden.

Second, the second-car effect suppresses current per-EV mileage figures. A large share of today’s EV owners use their electric vehicle for short trips and a second Internal Combustion Engine (ICE) vehicle for longer range, meaning total household vehicle-kilometers are split across two powertrains. Full conversion eliminates that division; every mile, including the longest trips, must be covered by electricity alone.

Third, plug-in hybrids inflate the current consumption baseline in the wrong direction. Many vehicles counted in current EV electricity statistics are PHEVs drawing only partial electricity, with the remainder supplied by gasoline. A full conversion replaces those vehicles with 100% electric demand, making current per-vehicle electricity figures an understatement of what full-EV usage would require.

Fourth, range anxiety suppresses demand today in ways that disappear under full conversion. Some ICE vehicle trips are taken specifically because charging availability or range constraints make the EV impractical for that use case. Full conversion forces all of those trips onto the electric grid regardless of infrastructure readiness.

Fifth, commercial and fleet vehicles carry far heavier duty cycles than the passenger cars dominating current EV data. Delivery vans, municipal buses, agricultural equipment, and construction vehicles operate at higher utilization rates and energy consumption per vehicle than consumer cars from which the 180 TWh baseline is derived. MIT Climate estimates that an all-electric vehicle fleet would account for between 13% and 29% of the United States’ total electricity use, already a multiple of what straight-line scaling from current EV data produces, and that figure covers only the U.S. passenger fleet, not global heavy transport.

For the U.S. alone, a full personal vehicle fleet conversion would require an expansion of the grid by approximately 1 to 2 trillion kWh, a 25 to 35% increase in total U.S. electricity demand. Extrapolated globally across a vehicle mix that is far more freight-heavy and infrastructure-poor than the U.S. passenger fleet, the true demand increase would be substantially larger than any figure derived from today’s 58 million predominantly passenger EVs.

Generating additional electricity is only part of the problem. That power must be transmitted from where it is generated to where millions of vehicles are parked and charging simultaneously, and the transmission system is not being built to handle current demand, let alone a fully electrified fleet. The DOE’s 2024 National Transmission Planning Study found the U.S. needs roughly 5,000 miles of new high-capacity transmission per year to support grid reliability and meet demand. In 2024, it built 888 miles, the third slowest year in 15 years.

Annual transmission spending has hit an all-time high of over $25 billion per year, yet the U.S. builds only 20% as much new transmission in the 2020s as it did in the first half of the 2010s, with the average falling from 1,700 miles per year from 2010 to 2014, to 925 miles from 2015 to 2019, to an average of just 350 miles per year from 2020 to 2023. Nearly 4,000 miles were built in 2013 alone. More money is being spent, less is being built, and the gap between what the grid requires and what is actually being constructed is widening every year. The DOE study calls for at least doubling regional transmission capacity and quadrupling interregional transmission capacity by 2050, before a single additional requirement from full EV conversion is factored in.

The second compounding problem is the fuel source of the grid that would actually be doing the charging. The implicit promise of EV policy is emissions reduction, but that promise depends entirely on what generates the electricity. The IEA confirms that fossil fuels made up nearly 60%  of 2024 global electricity generation, with coal alone accounting for 35%, the largest single source of electricity in the world, a position it has held for more than 50 years.

In 2024, global coal power generation reached nearly 10,700 TWh, a new record high. The countries that would absorb the majority of new vehicle electrification demand are precisely the most coal-dependent. In China, the world’s largest electricity system, coal provided almost 60% of generation in 2024. In India, coal provided nearly three-quarters of electricity supply.

A lifecycle assessment published in Nature’s Communications Earth & Environment found that in China’s coal-heavy northern provinces, the emission intensity of battery electric vehicles is higher than in southern provinces, with sulfur dioxide emissions increasing 10% and particulate matter 20% compared to internal combustion engine vehicles. Charging a global fleet on those grids does not eliminate vehicle emissions, it moves them from the tailpipe to the power plant, with transmission losses added on top.

The post Short-Sighted Climate Goals: It Is Impossible to Expand Electrical Grids to Support EV Conversion appeared first on The Gateway Pundit.

Go to Source
Author: Antonio Graceffo

New Study – Cannabis Causes Exponential Rise in the ‘Hole in the Heart’ Birth Defect

New Study – Cannabis Causes Exponential Rise in the ‘Hole in the Heart’ Birth Defect

New Study – Cannabis Causes Exponential Rise in the ‘Hole in the Heart’ Birth Defect
June 4, 2026

New study – Cannabis causes an exponential rise in ‘hole in the heart’ birth defect.

A landmark new study published by one of world’s most elite scientific journals, Nature – Journal of Perinatology, has demonstrated that rising US cannabis use is causally responsible for exponential increases in a birth defect commonly called ‘hole in the heart’ or Atrial Septal Defect (ASD), where US rates that measured 10.3 cases for every 10,000 births in 2005 have moved amongst certain ethnicities to as high as 884/10,000 in Nevada and Mississippi in 2020, or about 1 in 11 babies affected.

The study used careful statistical adjustments to show that the effect was truly causal. The findings are even more significant when it is recognized that many common birth defects lead to the termination of a pregnancy, whereas ASD generally doesn’t.  This means that the causal role of cannabis in this particular birth defect may be the canary in the coal mine, signaling not only the likely involvement of cannabis in other birth defects but that these rises in ASD rates are the bellwether marker for other cannabinoid genotoxic effects including human aging and some cancers.

In Nevada careful statistical modelling shows an exponential rate of rise.  Across the USA ASD rates are rising faster than exponentially.  As one reviewer of the paper wrote:

“… regarding statistical analysis and “causation” this manuscript has relevance to pediatric cardiologists, neonatologists, and above all to obstetricians who should more strongly advise against the use of cannabis (in any form) during pregnancy. Indeed, this reviewer believes that this is a landmark study, and with the revised data analysis, much more strongly points to causation rather than mere association. Extremely important for public health advisories against cannabis use during pregnancy (and most probably for paternal cannabis use during partner’s pregnancy).”

Other peer-reviewed cannabis population studies by the same researchers show that cannabis is causal in twice as many cancers as tobacco and numerous other birth defects in both Europe and the USA.  The effects on human ageing are extremely concerning indeed when rolled out across whole populations, including eggs, sperm and babies.

Says Gary Christian, President of Drug Free Australia,

“This is an issue that the media urgently needs to bring to the attention of the Australian people, given a heavy reliance in this country on medicinal cannabis, which presents all of these risks to both the childbearing and general populations.”

This is a discussion we urgently need to have.

The post New Study – Cannabis Causes Exponential Rise in the ‘Hole in the Heart’ Birth Defect appeared first on The Gateway Pundit.

Go to Source
Author: Joe Hoft

INSANITY: New York State Democrats Pass Bill Replacing the Words “Mother” and “Father” with These Two Ultra-Woke Terms

INSANITY: New York State Democrats Pass Bill Replacing the Words “Mother” and “Father” with These Two Ultra-Woke Terms

INSANITY: New York State Democrats Pass Bill Replacing the Words “Mother” and “Father” with These Two Ultra-Woke Terms
June 4, 2026

New York Gov. Kathy Hochul flanked by Democrat lawmakers as she announces support for so-called “medical aid in dying”

Democrats in New York State have declared war on the nuclear family after passing a bill designed to kowtow to the radical pro-trans lobby.

As The New York Post reported on Wednesday, the New York State Legislature this week passed legislation that would erase the terms “mother” and “father” from state child custody and parental laws in favor of two woke, gender-neutral terms.

The terms that would be used instead? Gestating parent and non-gestating parent.

This sounds like something straight out of the Babylon Bee.

The New York Post reported:

A woke new bill erases the terms “mother” and “father” from state child custody and parental laws — a gender-neutral rewriting that’s expected to spark a flood of similarly clunky legislation.

“Mother” would be replaced with “gestating parent,” while “father” becomes “non-gestating parent” or “parent” in family court, passed this week by state Democrats.

“Paternity” proceedings to determine a child’s biological father would meanwhile become “parentage” cases, under the bill, which was rammed through the Assembly in March and of the Senate this week.

A “putative father” — also known as a deadbeat dad — would now be called “an alleged parent” in official state records, under the bill, which was sponsored by liberals Sen. Luis Sepulveda (D-Bronx) and Assemblywoman Amy Paulin (D-Westchester) and will go to Gov. Kathy Hochul’s desk for approval.

Sepulveda, a Bronx Democrat who chairs the Senate Judiciary Committee, claimed the bill was necessary “to be consistent with current statute and case law>

Republican gubernatorial candidate Bruce Blakeman lashed out at the changes:

“Democrats led by Kathy Hochul have continued their declaration of war on New York families by canceling the loving terms of Mom and Dad and replacing them with ‘gestating and non-gestating parent,’” Blakeman said in a statement obtained by the New York Post.

“The insanity ends when I’m Governor.”

For her part, Hochul pleaded ignorance and refused to say whether she would sign the bill.

“Well, I’m not familiar with what was introduced,” she told reporters at an event in Brooklyn on Wednesday.

“I’ll take a look at it. This has been my practice for five years.”

The post INSANITY: New York State Democrats Pass Bill Replacing the Words “Mother” and “Father” with These Two Ultra-Woke Terms appeared first on The Gateway Pundit.

Go to Source
Author: Cullen Linebarger

Economic Analysis: Indicators Suggest China’s Economy Will Not Surpass the U.S.

Economic Analysis: Indicators Suggest China’s Economy Will Not Surpass the U.S.

Economic Analysis: Indicators Suggest China’s Economy Will Not Surpass the U.S.
June 4, 2026

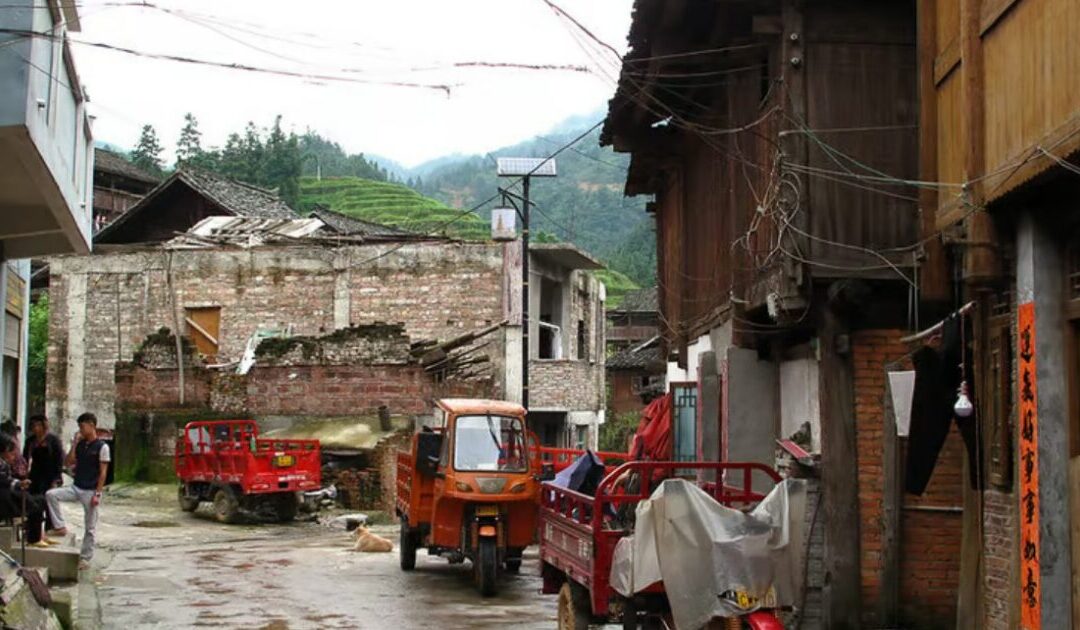
Rural street scene featuring colorful three-wheeled vehicles, traditional wooden buildings, and lush green mountains in the background.
China’s return on investment has declined steadily and is now negative in many cases. Economic indicators suggest the Chinese economy will never overtake the U.S. economy. Photo courtesy of The Borgen Project.

China’s economy is often described as an unstoppable force that will inevitably displace the United States as the world’s dominant economic power. However, this belief is not supported by the data.

For roughly four decades, China has channeled approximately 40 percent of GDP annually into state-directed investment, a ratio with no precedent among major modern economies. The World Bank puts China’s gross fixed capital formation at 40.45 percent of GDP in 2023, against a U.S. figure of 21.6 percent. What that investment once produced in growth, it no longer delivers.

Investment is beneficial if it yields a return, but China’s return on investment has been declining for decades and is now negative in some cases. The measure economists use to assess investment efficiency is the Incremental Capital-Output Ratio, the amount of investment required to generate one additional dollar of GDP growth. Research documented by Fortune shows China’s ICOR rose 50 percent, from 2.6 during 1979–1996 to 4.0 during 1997–2013, meaning that before 1997 China needed $2.60 in investment to generate one dollar of GDP growth, against $4.00 in the later period.

Brookings finds the ICOR has since tripled from 3 to 9 since 2007, while GDP growth has fallen by half. The same researchers found the delivery rate of completed capital projects had fallen below 60 percent from 74–79 percent in the late 1990s, with nearly 40 percent of Chinese investment projects either unfinished or not completed on time, and estimated that ineffective investment had cost China $6.8 trillion in wasted post-2009 stimulus alone.

Capital Economics confirms that China’s ICOR has soared in recent years as investment has become increasingly inefficient. Capital inputs now contribute less than 3 percentage points to annual GDP growth, down from nearly 6 percentage points earlier in the prior decade, per the Federal Reserve Bank of New York’s Liberty Street Economics.

A peer-reviewed analysis published in the Journal of Development Economics found that infrastructure expansion accounts for 14 percent of China’s average annual growth rate over the period 2003–2016, but the expansion was socially excessive for nearly the entire period, with low and negative marginal contributions recorded for some regions and infrastructure types, per a separate ScienceDirect study.

The Carnegie Endowment concludes that China’s GDP growth is an input, a number decided early in the year and then achieved through whatever intervention is necessary, with non-productive investment carried at cost rather than written down, converting losses into fictitious assets, per a second Carnegie analysis. High-speed rail illustrates the point: expansion has significantly outpaced passenger growth, despite the 6 trillion yuan in liabilities and continuous financial losses at the China State Railway Group, per Stanford’s FSI China Briefs.

In a market economy, unproductive investment contracts through bankruptcy and credit withdrawal. In China’s state-directed system it expands. Rhodium Group’s China Pathfinder Q1 2024 documented that subsidies and credit forbearances raised the share of loss-making industrial enterprises from 15 percent in 2021 to 22 percent in 2023, with the March 2024 Government Work Report showing no sign of changing course. Researchers at the Federal Reserve Bank of Dallas estimated that the share of zombie firms across the broader economy reached 16 percent in 2024, up from 5 percent in 2018, with the real estate sector particularly distressed, figures cited and confirmed by the Atlantic Council, which reported the Dallas Fed finding that roughly 40 percent of bank loans to the real estate sector in 2024 went to companies whose operating earnings could not cover their interest obligations, up from just 6 percent in 2018, with most loans rolled over rather than recognized as losses.

Stanford’s FSI China Briefs documents that China’s banks allocate 80 percent of loans to state-owned enterprises, which show higher levels of bad debt than private firms, a pattern established through analysis of over 300,000 business loans issued by 1,500 branches of a large Chinese state bank between 1997 and 2010.

The IMF’s 2024 Article IV assessment found that corporate leverage and indebtedness indicators are highest for central SOEs, with an aggregate liability ratio of 66 percent of total assets in 2023. A State Council report submitted to the National People’s Congress, confirmed by Global Times, records non-financial SOE combined liabilities at RMB 260.5 trillion at end-2024, against China’s nominal GDP of approximately RMB 134 trillion.

The real estate market, which once anchored the investment model, has collapsed. The Atlantic Council reports the slump is in its fifth year with no recovery in sight, sales, prices, construction starts, and completions continue to slide, with an estimated 80 million unsold or vacant homes and more than 60 developers having defaulted on offshore debt or entered restructuring. Between 2024 and 2025, investment in real estate development fell 10.6 percent. Government-linked developer China Vanke posted a record ¥49.5 billion ($6.8 billion) loss for 2024, and Evergrande was delisted from the Hong Kong Stock Exchange following court-ordered liquidation.

The debt accumulated by four decades of state-directed investment is without parallel. China’s macro leverage ratio reached 302.3 percent in 2025, per the National Institution for Finance and Development. The IMF’s Article IV Consultation puts the figure at 312 percent of GDP in 2024, up from 245 percent in 2019, placing China among the most indebted countries in the world. The Carnegie Endowment notes that China accounts for more than half of the increase in the global economy’s debt-to-GDP ratio since 2008. Total U.S. public and private debt stood at approximately 265 percent of GDP in 2024, down from pandemic-era highs, per the BEA.

Those figures exclude the off-balance-sheet debt Beijing has systematically kept off government books. Local Government Financing Vehicles, entities created by local governments to borrow outside Beijing’s annual debt quotas, carry hidden liabilities the IMF estimates at RMB 60 trillion ($8.4 trillion), approximately four times the RMB 14.3 trillion Beijing’s Finance Ministry acknowledges. BBVA Research places the figure higher, at RMB 78 trillion as of Q3 2024, equivalent to 58 percent of China’s GDP. Broad shadow banking assets rose to RMB 53.3 trillion in 2024 from RMB 49 trillion in 2023. China’s augmented fiscal deficit, which captures LGFV debt and special bond issuance excluded from the official 4 percent figure, runs at approximately 10 percent of GDP according to Fitch, which downgraded China’s sovereign rating from A+ to A in 2024.

The gap between the two economies is visible in every per-capita measure. World Bank 2024 data puts U.S. GDP per capita at $84,534 against China’s $13,303, a ratio of 6.4 to 1. The consumption gap is wider. U.S. personal consumption expenditure per capita reached $58,501 in 2024, per the Bureau of Economic Analysis, against $4,802 in China per the National Bureau of Statistics, a ratio of approximately 12 to 1. The structural reason is that Chinese households consume only 39.1 percent of GDP against approximately 70 percent in the United States, meaning a far larger share of what China produces goes to investment and government spending rather than household income. The U.S. generates 2.8 percent annual growth investing 21.6 percent of GDP; China reports 5 percent growth investing nearly double that share.

China’s growth rate has been decelerating for over a decade. A decade ago China posted 7–8 percent annual growth against U.S. growth of roughly 2–2.5 percent, a differential of 5–6 percentage points.

Demographics compound every structural constraint. In 2025, China recorded 7.92 million births against 11.31 million deaths, a net population decline of 3.39 million. The working-age population (16–59) fell by approximately 6.62 million year-on-year and now accounts for 60.6 percent of the population, per the China NBS. Oxford Economics, cited by Newsweek, projects China’s potential output growth will fall below 4 percent in the 2030s and under 3 percent in the 2040s. The IMF estimates that China’s aging workforce could curtail total factor productivity growth by 0.3 percent per year from 2020 to 2050. China’s fertility rate was estimated at 1.2 births per woman in 2024, well below the 2.1 replacement level, per the UN World Population Prospects 2024. CSIS ChinaPower projects China’s population will shrink by over 100 million by 2050.

The case that China will surpass the United States rests on extrapolating past growth rates into a future where the conditions that produced them no longer exist. The investment model is generating diminishing and in some cases negative returns. The debt is compounding. As the IMF’s 2025 Article IV stated directly, slowing productivity growth, high corporate and public debt levels, decreasing returns to investment, and an aging population, taken together, point to slower growth going forward.

The post Economic Analysis: Indicators Suggest China’s Economy Will Not Surpass the U.S. appeared first on The Gateway Pundit.

Go to Source
Author: Antonio Graceffo

SILVER SCREEN TABOO: Legendary Film Director Marin Scorsese Under Fire for Joining Forces With AI Company

SILVER SCREEN TABOO: Legendary Film Director Marin Scorsese Under Fire for Joining Forces With AI Company

SILVER SCREEN TABOO: Legendary Film Director Marin Scorsese Under Fire for Joining Forces With AI Company
June 4, 2026

AI-Generated Image by Grok

Scorsese, the purist, surprises Tinseltown.

If there is one subject that unites the ultra-liberal Hollywood elites is their absolute hatred for Generative AI.

It is seen, for good reason, as a direct threat to writers, actors, and artists.

But this week, Hollywood was shaken by a magnitude-9 earthquake: 83-year-old Martin Scorsese, 16-time Oscar nominee, revealed that, since last year, he has become a partner and advisor at Black Forest Labs, an AI image generation startup.

That sent industry figures and film fans reeling.

Scorsese joins a small but growing wave of artists who are supporting AI, such as Demi Moore, Darren Aronofsky, and Ben Affleck.

TMZ reported:

“The famed director announced Tuesday he will be using the company’s tech to help create storyboards … and some folks say they’re feeling let down that he’s embracing A.I. into the creative process.”

“Black Forest Labs shared a video from a storyboarding session they had with Martin … where the filmmaker described his vision, and they used A.I. to create the scene.

[…] In a statement, Martin explains … ‘For 70 years, I’ve been creating my own storyboards. There’s always been this problem of how do you communicate what you see in your head to your cast and crew. There are some things you have to see and feel’.”

Needless to say, crying and grinding of teeth are heard around Hollywood, as critics warn this partnership will take work away from real-life, human storyboard artists.

Read more:

Hollywood Legend Val Kilmer Dead at 65

The post SILVER SCREEN TABOO: Legendary Film Director Marin Scorsese Under Fire for Joining Forces With AI Company appeared first on The Gateway Pundit.

Go to Source
Author: Paul Serran